For decades, the 60/40 portfolio (60% stocks, 40% bonds) has been standard investment advice. It’s simple, intuitive, and has historically served investors well. It also has a flaw: a 60/40 portfolio balances capital while leaving risk lopsided.
In practice, the volatile equity portion often contributes over 90% of the total portfolio’s risk. That leaves investors heavily exposed to stock market downturns, as in 2008 and 2022, when traditional diversification failed to protect capital.
Risk parity investing is a more resilient alternative. It shifts the focus from capital allocation to risk allocation. Instead of asking “How much money should I put in each asset?” it asks, “How much risk should each asset contribute to my portfolio?”
This guide explains how risk parity works, what it offers for portfolio stability, the main risks involved, and how you can apply its principles. We’ll also look at why this institutional-grade strategy is drawing more interest from investors seeking consistent, long-term growth in an uncertain world. Any advanced strategy needs a disciplined approach to strategic portfolio rebalancing for wealth growth to keep its intended balance.
Table of Contents
Open Table of Contents
- What is Risk Parity? A Fundamental Shift from Capital to Risk
- The Three Pillars of Risk Parity Portfolio Construction
- Risk Parity vs. The 60/40 Portfolio: A Head-to-Head Comparison
- Key Benefits of a Risk Parity Strategy
- The Critical Risks and Constraints (And How to Mitigate Them)
- Implementing a Risk Parity Strategy: A Practical Guide
- Who is Risk Parity Best For? (And Who Should Avoid It)
- Conclusion: Beyond Diversification and Building a Truly Resilient Portfolio
What is Risk Parity? A Fundamental Shift from Capital to Risk
Risk parity is an investment strategy that gives each asset class in a portfolio an equal share of the total portfolio risk. This balancing of risk contributions is the strategy’s defining feature.
Consider the 60/40 portfolio again. You hold 60% of your capital in stocks, and their historical volatility is roughly three to five times higher than that of high-quality government bonds, so equity risk dominates the portfolio. When stocks fall, the entire portfolio suffers significantly.
A risk parity strategy corrects this imbalance. Different assets carry different levels of inherent risk (volatility), so a balanced risk profile means allocating more capital to lower-risk assets (like bonds) and less capital to higher-risk assets (like stocks).
For example, if stocks are three times as volatile as bonds, a risk parity approach might allocate three times as much capital to bonds as it does to stocks to make their risk contributions equal. The portfolio is then diversified in terms of risk, which a simple count of assets does not show.
The Three Pillars of Risk Parity Portfolio Construction
To move from theory to application, we use a proprietary framework, The Risk Contribution Equilibrium (RCE) Framework, which breaks the process into three pillars.
Pillar 1: Measure True Risk Contribution
The first step is to quantify the risk of each asset class. In professional finance, “risk” is most commonly measured by volatility, or the standard deviation of returns. An asset with high volatility experiences larger price swings and is considered riskier.
This involves analyzing the historical volatility of each potential component of your portfolio:
- Domestic & International Equities
- Long-Term Government Bonds
- Inflation-Protected Bonds (TIPS)
- Commodities
- Real Estate Investment Trusts (REITs)
The goal is a clear, data-driven picture of how much each asset class moves up and down over time.
Pillar 2: Allocate Capital to Balance Risk
Once you know the relative volatility of each asset, you allocate capital using an inverse-volatility weighting.
- High-Volatility Assets (e.g., Stocks): Receive a smaller capital allocation.
- Low-Volatility Assets (e.g., Bonds): Receive a larger capital allocation.
This ensures that no single asset class can dominate the portfolio’s behavior. The aim is equilibrium, where the expected risk from your equity sleeve equals the risk from your bond sleeve and from your commodities sleeve. This often involves looking into alternative investments for strategic diversification to find uncorrelated sources of risk and return.
Pillar 3: Apply Leverage to Target Desired Returns
A portfolio built this way is well diversified but often has a high allocation to low-return assets like bonds, so its expected return might be too low for many investors’ goals.
Leverage is the most controversial and misunderstood component of risk parity.
To achieve equity-like returns, the entire balanced portfolio is often levered up. For example, if the risk-balanced portfolio has an expected volatility of 5%, and an investor wants the 15% volatility typical of an all-stock portfolio, they might apply 3x leverage.
Here leverage scales up the risk and return profile of an already highly diversified, low-risk portfolio, and it is never aimed at a single speculative asset.
Risk Parity vs. The 60/40 Portfolio: A Head-to-Head Comparison
The structural differences between risk parity and traditional allocation explain its potential advantages and trade-offs.
| Feature | Traditional 60/40 Portfolio | Risk Parity Strategy |
|---|---|---|
| Core Principle | Balance capital allocation between stocks and bonds. | Balance risk contribution from all asset classes. |
| Asset Allocation Driver | Predetermined capital percentages (60%, 40%). | Inverse volatility of assets. |
| Role of Bonds | Primarily for income and a small diversification benefit. | A core driver of returns, equally weighted by risk. |
| Use of Leverage | Generally avoided; 100% funded. | Often used to scale the entire portfolio’s return profile. |
| Performance in Bull Markets | Tends to perform very well when led by strong equity gains. | May lag in powerful, narrow bull markets due to diversification. |
| Performance in Crashes | Highly vulnerable to equity market crashes. | Designed for better downside protection and smaller drawdowns. |
| Diversification Method | Asset class diversification. | True risk factor diversification. |
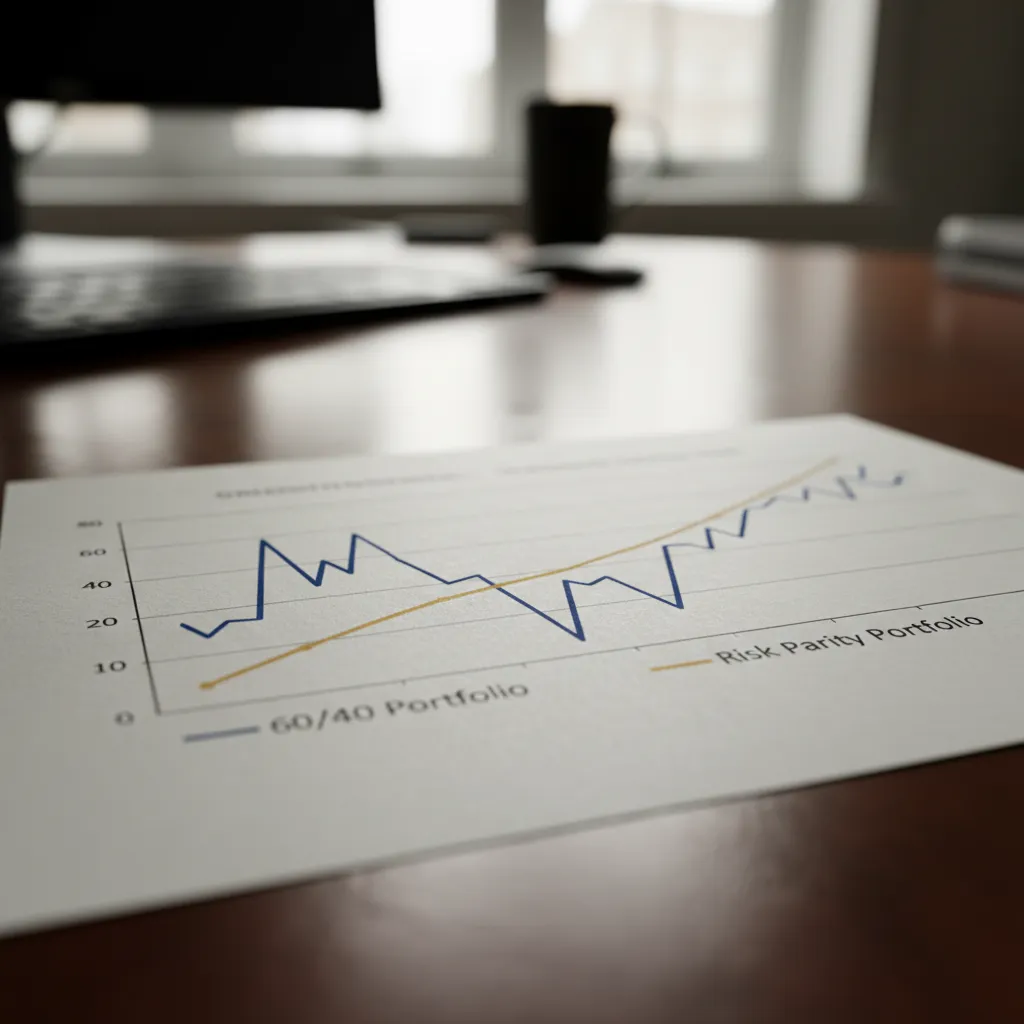
The 60/40 is simpler and can be very effective during long periods where stocks outperform and bond correlations remain negative. A risk parity strategy is built to hold up across more varied economic environments, including periods of rising inflation where both stocks and bonds can fall together. That makes it a useful tool for strategic inflation hedging to protect wealth.
Key Benefits of a Risk Parity Strategy
A risk parity approach offers several advantages for the long-term investor focused on stability and consistent compounding.
- Superior Diversification: It provides true risk diversification, reducing dependency on the performance of a single asset class. Your portfolio’s health no longer hinges almost exclusively on the stock market.
- Improved Risk-Adjusted Returns: The primary goal is better returns for each unit of risk taken. Over full market cycles, risk parity strategies often exhibit a higher Sharpe ratio than traditional portfolios.
- “All-Weather” Performance: By balancing risk across assets that perform differently in various economic regimes (e.g., growth, recession, inflation, deflation), the portfolio is designed to achieve positive returns more consistently.
- Reduced Drawdowns: Perhaps its most attractive feature is the potential for smaller losses during market downturns. By avoiding over-concentration in equities, risk parity can help preserve capital when it matters most.
The Critical Risks and Constraints (And How to Mitigate Them)
Risk parity is no “free lunch.” Its structure brings a different set of risks that investors need to understand and accept.
1. Leverage Risk
This is the most significant concern. Leverage is applied to a diversified portfolio, but it still magnifies both gains and losses.
- Mitigation: Individual investors should be extremely cautious with DIY leverage. A more prudent approach is to access the strategy through professional funds where leverage is managed at an institutional level. Investors can also opt for unlevered or low-leverage versions of the strategy and accept lower returns for lower risk.
2. Interest Rate Sensitivity
Because risk parity portfolios often hold large positions in long-duration bonds, they can be vulnerable to sharp, unexpected increases in interest rates. The bond market turmoil of 2022 demonstrated this risk clearly.
- Mitigation: A well-constructed risk parity portfolio includes inflation-protected bonds (TIPS) and commodities, which tend to perform well when rates rise because of inflation. This diversification helps buffer the impact on the traditional bond portion.
3. Correlation Risk
The strategy’s effectiveness relies on the diversification benefits between asset classes. In a systemic crisis (like March 2020), correlations can spike, and all assets may fall simultaneously.
- Mitigation: No strategy is immune to a systemic crisis, but risk parity is arguably more resilient than a 60/40 portfolio. Its balance means it does not depend solely on the stock-bond correlation, so it spreads its bets more widely.
4. Complexity and Costs
Implementing and managing a risk parity portfolio is far more complex than buying a couple of index funds, and funds offering these strategies tend to have higher expense ratios. When considering costs, it’s wise to understand all wealth management fees to optimize value.
- Mitigation: Weigh the potential for smoother returns and downside protection against the higher fees. For many investors, the added cost is a worthwhile price for a more stable investment journey.
Implementing a Risk Parity Strategy: A Practical Guide
For individual investors, there are two primary paths to implementing a risk parity strategy.
Step 1: Define Your Asset Classes
A risk parity portfolio should include a broad set of global assets that behave differently in various economic conditions.
- Global Equities
- Long-Term Government Bonds
- Inflation-Protected Bonds (TIPS)
- Commodities (Gold, Broad Baskets)
- Real Estate (e.g., how to invest in REITs strategically)
Step 2: Choose Your Implementation Method
- The Fund Approach (Recommended for Most Investors): The simplest and safest method is to invest in mutual funds or ETFs specifically designed around risk parity principles. Look for funds with names like “Risk Parity,” “All-Weather,” or “Multi-Asset.” Read their fact sheets closely to understand their holdings, leverage levels, and expense ratios.
- The DIY Approach (Advanced Investors Only): This path requires significant expertise. It involves using a brokerage account to buy individual ETFs for each asset class, calculating their volatility, determining the correct inverse-volatility weightings, and applying leverage through margin or futures contracts. This approach carries substantial risks and is not recommended without deep financial knowledge.
Step 3: Set a Rebalancing Schedule
Like any disciplined strategy, risk parity requires regular rebalancing. As market movements shift the risk balance of your portfolio, you’ll need to sell assets that have become “too risky” and buy those that are now “less risky” to return to your target equilibrium. A quarterly or semi-annual rebalancing schedule is a common practice.
Who is Risk Parity Best For? (And Who Should Avoid It)
Risk parity does not suit every investor profile.
Ideal Candidate Profile:
- Investors Prioritizing Capital Preservation: Those who are more concerned with avoiding large losses than capturing every bit of market upside.
- Retirees and Pre-Retirees: These investors are highly sensitive to “sequence of return risk,” where a large drawdown early in retirement can be devastating, so the smoother return profile of risk parity appeals to them. See how this fits into a larger plan for strategic retirement planning for financial freedom.
- Long-Term, Process-Oriented Investors: Those who understand the strategy’s logic and have the discipline to stick with it, even during periods when it may underperform simpler, equity-heavy portfolios.
Who Should Be Cautious:
- Young Investors with High Risk Tolerance: A 25-year-old with a 40-year time horizon may achieve higher terminal wealth with a 100% equity portfolio, assuming they have the stomach to endure severe drawdowns.
- Investors Uncomfortable with Leverage: If using any form of leverage, even on a diversified portfolio, is psychologically unsettling, this strategy may not be a good fit.
- Performance Chasers: Investors who cannot tolerate underperforming the S&P 500 during a roaring bull market will likely abandon the strategy at the worst possible time.
If you’re unsure how this strategy fits your personal financial situation, choosing a fiduciary financial advisor for unbiased advice can help.
Conclusion: Beyond Diversification and Building a Truly Resilient Portfolio
Risk parity investing changes how portfolios are built. It moves away from the deceptive simplicity of capital allocation and toward the more logical framework of risk allocation. By building a portfolio where each component has an equal voice in the overall risk profile, investors can create a more durable engine for wealth creation.
Risk parity involves trade-offs: it may lag in speculative bull markets in exchange for stronger protection in downturns. It requires an understanding of its mechanics, particularly the role of leverage, and a long-term commitment to its principles.
With geopolitical uncertainty rising, inflation dynamics shifting, and markets volatile, the question for investors is whether their diversification is effective. Risk parity offers one answer: a strategic blueprint for a portfolio that is structurally resilient to future crises as well as the last one.
This article is general information, not financial, investment, tax or legal advice. Your situation is your own, so check with a qualified professional before you act on it. See our disclaimer.