Financial independence often feels abstract, a distant goal for a select few. But you can build a system that generates income in the background while you focus on your career, family, and passions. That is what a disciplined, long-term approach to dividend investing produces.
Many investors chase fleeting trends and volatile “growth” stocks and ride the swings of market sentiment. Dividend investing takes a business-owner’s view of the market. You own a piece of a profitable enterprise that shares its success with you, quarter after quarter, and that steady cash flow can become the base of lasting wealth.
This guide goes past simplistic lists of “best dividend stocks.” We cover the durable frameworks and dividend investing strategies you need to build a resilient passive income engine: the core philosophies, how to construct a diversified portfolio, and how to optimize for taxes. A strong financial footing is the first step, and building it can even help you improve your credit score and financial empowerment, which sets the stage for investing.
Table of Contents
Open Table of Contents
- Why Dividend Investing is More Than Just Collecting Checks
- The Core Dividend Investing Strategies: Finding Your Fit
- The “Resilient Income Stream” Framework: A Blueprint for Your Portfolio
- Building Your Dividend Portfolio from the Ground Up
- Advanced Tactics: Tax Efficiency and Risk Management
- Getting Started: A Practical Checklist for Dividend Investing for Beginners
- Common Mistakes to Avoid on Your Dividend Journey
- Conclusion: Your Journey to Financial Independence Starts Now
Why Dividend Investing is More Than Just Collecting Checks
A dividend is a distribution of a company’s earnings to its shareholders. It also works as a signal about the company and as a major component of total return.
1. A Sign of Financial Health and Discipline: Companies that pay dividends consistently, and especially those that raise them year after year, are typically mature, stable, and profitable. They have predictable cash flows and a management team committed to shareholder returns. A dividend policy also forces financial discipline and keeps executives from spending cash on low-return projects.
2. The Power of Compounding: Compounding is where dividend investing earns most of its value. When you reinvest your dividends, you buy more shares. Those new shares generate their own dividends, which buy still more shares. Over time this produces an exponential growth curve and speeds up your wealth accumulation without a single additional dollar from your pocket.
3. Total Return Engine: An investor’s total return is the sum of capital appreciation (the stock price going up) and dividends. In flat or volatile markets, dividends give you a steady source of return, smooth out portfolio performance, and act as a psychological buffer against market panic. Over long periods, reinvested dividends have historically accounted for a significant portion of the S&P 500’s total return.
4. A Hedge Against Inflation: Inflation erodes the value of a savings account, while a portfolio of companies that grow their dividends can provide a rising stream of income that keeps pace with the cost of living. That makes passive income dividend stocks a useful tool for retirees and anyone who wants to preserve purchasing power over decades.
The Core Dividend Investing Strategies: Finding Your Fit
Dividend strategies differ, and the right one depends on your age, risk tolerance, and financial goals. Understanding the main methods is the first step toward a personalized dividend portfolio.
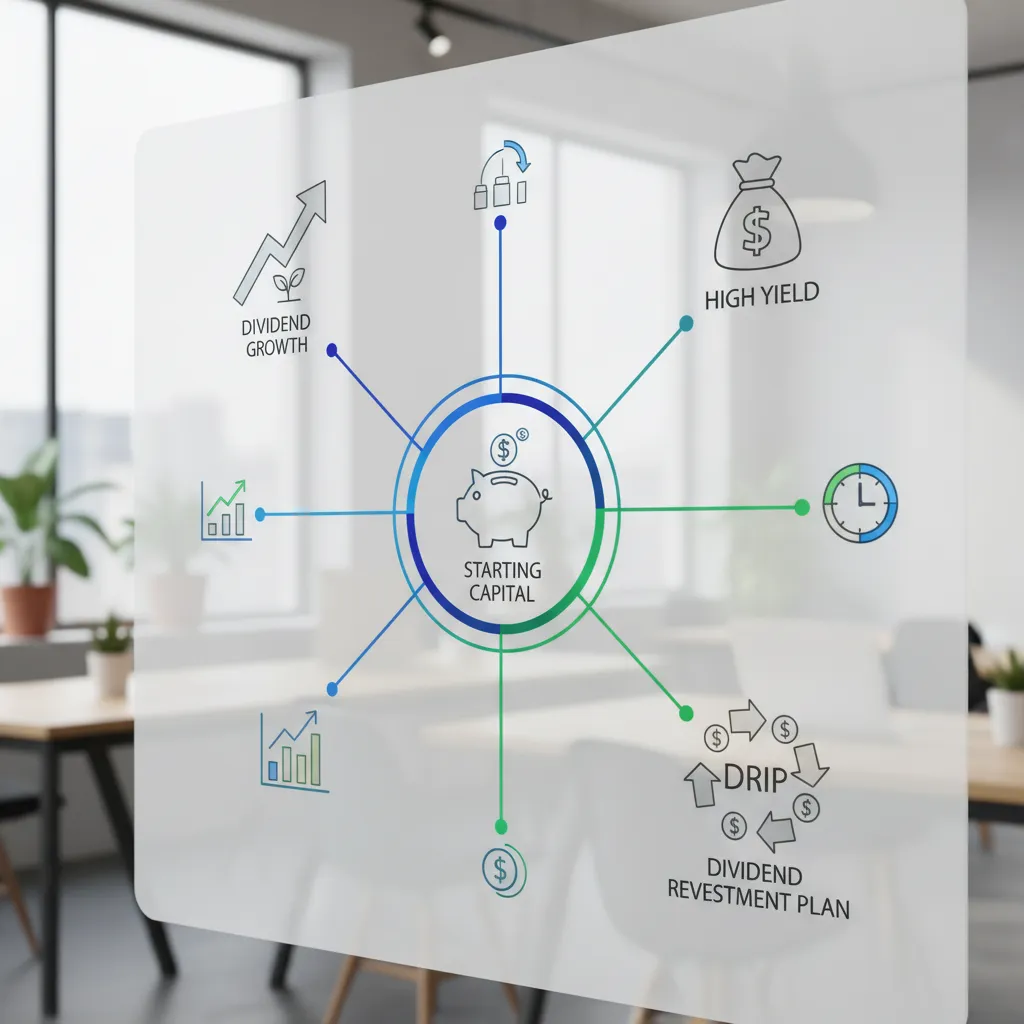
Dividend Growth Investing: The Compounding Powerhouse
This strategy is the gold standard for long-term investors. It favors companies with a proven record of increasing their dividends each year. The initial dividend yield may be modest (e.g., 1-3%), but the focus is on how fast that dividend grows.
- Who it’s for: Younger investors with a long time horizon who want to build significant wealth through compounding.
- Key Concept: Yield on Cost (YOC). Your YOC is the annual dividend per share divided by your original purchase price. As a dividend growth company raises its payout year after year, your YOC can climb a long way. A stock you bought with a 3% yield might have a 10%, 15%, or even 20% YOC after a decade or two.
- Where to look: Look for “Dividend Aristocrats” (S&P 500 companies with 25+ consecutive years of dividend increases) and “Dividend Kings” (50+ years). These are typically blue-chip leaders in stable industries.
High-Yield Dividend Investing: Maximizing Immediate Income
This approach targets stocks with dividend yields well above the market average (e.g., 5%+). It appeals to people who want the most current income.
- Who it’s for: Retirees or investors who need to generate substantial passive income from their portfolio today.
- The warning: the “Yield Trap.” A very high yield can be a red flag. It may mean the stock price has fallen sharply because of underlying business problems, which puts the dividend at risk of a cut. Always investigate why the yield is so high. Is the company’s payout ratio (the percentage of earnings paid as dividends) dangerously high? Is the business in a declining industry?
- Where to look: Sectors like Real Estate Investment Trusts (REITs), Master Limited Partnerships (MLPs), Business Development Companies (BDCs), and Utilities often feature high yield dividend stocks.
Dividend Reinvestment Plans (DRIP): Automating Your Wealth Engine
A DRIP investing strategy is less a stock-selection method than an execution tactic. It automatically uses your dividend payments to buy more shares of the same stock, often in fractional amounts.
- Who it’s for: Every long-term dividend investor.
- Key Benefits:
- Frictionless Compounding: Your money goes back to work immediately without any effort from you.
- Dollar-Cost Averaging: You automatically buy more shares when the price is low and fewer when it is high.
- Psychological Advantage: It removes the temptation to spend dividend income and keeps your long-term plan on track.
Most modern brokerage accounts let you enable a dividend reinvestment plan for any dividend-paying stock with a single click.
The “Resilient Income Stream” Framework: A Blueprint for Your Portfolio
A strong, diversified dividend portfolio needs a strategic allocation model, and a random collection of stocks is not one. The “Resilient Income Stream” Framework sorts your holdings by their role in the portfolio, so you get a balance of safety, growth, and income.
| Portfolio Tier | Role | Typical Allocation | Characteristics | Examples (Illustrative) |
|---|---|---|---|---|
| Core Holdings | The Bedrock | 50-60% | Dividend Aristocrats/Kings, stable blue-chips, low payout ratios, steady growth. | Johnson & Johnson, Procter & Gamble, Coca-Cola |
| Growth Accelerators | The Boosters | 20-30% | Lower starting yield but high dividend growth rate (10%+ annually). | Microsoft, Apple, Home Depot |
| Income Maximizers | The Cash Flow | 10-20% | High current yield (5%+), requires more due diligence. | Well-vetted REITs, Utilities, BDCs |
With this split, most of your portfolio is anchored in safe, reliable growers, while smaller portions are set aside to speed up dividend growth and raise your current income.
Building Your Dividend Portfolio from the Ground Up
Knowing the strategies is one thing, and executing them is another. Here is how to go from concept to a real portfolio.
Step 1: Define Your Financial Goals and Timeline
Before you buy a single share, answer these questions:
- What is this money for? Retirement income? A down payment in 10 years? General wealth building?
- What is your timeline? An investor in their 20s can prioritize Growth Accelerators, while someone five years from retirement will lean more on Core Holdings and Income Maximizers.
- What is your risk tolerance? Can you stomach market volatility, or do you prefer a smoother ride? Your answer will shape your allocation to higher-yield, higher-risk assets.
Step 2: Vetting and Analyzing Dividend Stocks
This is where you put on your analyst hat. Yield alone tells you little, so dig into the fundamentals to assess the dividend’s safety and growth potential.
- Dividend Yield: The annual dividend per share divided by the current stock price. A useful starting point, but never the only factor.
- Payout Ratio: The percentage of a company’s earnings paid out as dividends. A ratio below 60% is generally considered healthy and sustainable, because it leaves room to reinvest in the business and raise the dividend. For REITs, use Funds From Operations (FFO) instead of earnings.
- Dividend History: How many consecutive years has the company paid and increased its dividend? A long history points to stability and commitment to shareholders.
- Earnings and Revenue Growth: A company can’t grow its dividend long-term if its profits aren’t growing. Look for consistent top-line and bottom-line growth. Analyzing these trends with data matters, and modern tools now apply AI to make financial forecasting for strategic decisions more accurate.
- Balance Sheet Health: Look for manageable debt levels (e.g., Debt-to-Equity ratio). A company buried in debt may have to cut its dividend during an economic downturn.
- Competitive Moat: Does the company have a durable competitive advantage (brand recognition, network effects, patents) that protects its profitability?
Step 3: Diversification is Your Only Free Lunch
Never concentrate your portfolio in a single company or industry. A dividend cut at one company should be a minor event.
- Sector Diversification: Own stocks across sectors like Technology, Healthcare, Consumer Staples, Industrials, and Financials. This protects you if one sector faces headwinds.
- Geographic Diversification: Consider including international dividend-paying companies or ETFs to reduce your dependence on the U.S. economy alone.
Advanced Tactics: Tax Efficiency and Risk Management
As your portfolio grows, its structure matters more for your real, after-tax returns.
Understanding Qualified vs. Non-Qualified Dividends
In the U.S., dividends are not all taxed equally.
- Qualified Dividends: These are paid by most U.S. corporations and many foreign ones. They are taxed at the lower long-term capital gains rates (0%, 15%, or 20%, depending on your income).
- Non-Qualified (Ordinary) Dividends: These are taxed at your higher, ordinary income tax rates. Dividends from REITs, MLPs, and BDCs often fall into this category.
Knowing the difference is the basis of tax efficient dividend investing.
Strategic Asset Location
The most effective tax strategy is placing your assets in the right type of account.
- Tax-Advantaged Accounts (401k, IRA): This is the ideal home for tax-inefficient assets. Place your REITs, BDCs, and other high-yield holdings that generate non-qualified dividends here. Inside these accounts, their income grows tax-deferred or tax-free.
- Taxable Brokerage Accounts: Hold your most tax-efficient investments here, mainly dividend growth investing stocks that pay qualified dividends.
This separation can save you thousands of dollars in taxes over the life of your portfolio.
Managing Portfolio Risks
Dividend investing is a lower-risk strategy, but it carries risk.
- Interest Rate Risk: When interest rates rise, “safer” investments like bonds become more attractive, which can put temporary downward pressure on the stock prices of stable, high-yield dividend payers like utilities.
- Dividend Cuts: This is the biggest risk, and it is why thorough vetting of a company’s fundamentals and payout ratio is required.
- Concentration Risk: As mentioned, a lack of diversification is an unforced error. Review your portfolio regularly to make sure no single position has grown into an outsized share of your holdings. Tools for AI investment portfolio optimization strategies can help you spot and reduce these concentration risks before they become a problem.
Getting Started: A Practical Checklist for Dividend Investing for Beginners
If you feel overwhelmed, the question of how to start dividend investing is simpler than it looks. You can begin in a single afternoon.
- Open a Brokerage Account: Choose a reputable, low-cost online broker like Fidelity, Vanguard, or Charles Schwab. The process is entirely online and takes minutes.
- Fund the Account: Start with an amount you’re comfortable with. You don’t need thousands of dollars; you can start with as little as $100. What matters is starting.
- Make Your First Investment (The Easy Way): The simplest and safest way to begin is with a low-cost, broad-market dividend ETF (Exchange Traded Fund). Funds like the Schwab U.S. Dividend Equity ETF (SCHD) or the Vanguard Dividend Appreciation ETF (VIG) give you instant diversification across hundreds of high-quality dividend stocks.
- Research Your First Individual Stock: Once you’re comfortable, use the vetting criteria above to research a single, high-quality “Core Holding” like a Dividend Aristocrat.
- Enable DRIP: For every stock and ETF you buy, go into your account settings and turn on the Dividend Reinvestment Plan. Automate your compounding from day one.
- Automate Your Contributions: Set up a recurring automatic transfer from your bank account to your brokerage account every month or every payday. Paying yourself first is the most effective habit for long-term success.
Common Mistakes to Avoid on Your Dividend Journey
- Chasing Seductive Yields: If a dividend yield seems too good to be true, it probably is. Never invest based on yield alone.
- Ignoring Total Return: A 10% dividend is worthless if the stock price drops 30%. Always evaluate a company’s potential for both income and capital growth.
- Forgetting to Diversify: Falling in love with one or two stocks invites trouble. Spread your risk.
- Overlooking Taxes: Failing to use tax-advantaged accounts correctly is like throwing away free money.
- Panic Selling: Dividend investing is a long-term game. Market downturns are opportunities to buy more shares of great companies at a discount, so they are a poor reason to sell.
Conclusion: Your Journey to Financial Independence Starts Now
A substantial stream of passive income from dividend investing does not require Wall Street expertise. It comes from a disciplined process: selecting quality businesses, reinvesting the profits they share with you, and giving compounding time to work.
By focusing on dividend growth, managing risk through diversification, and optimizing for taxes, you build a personal financial engine. Every dividend you reinvest is a new employee working to generate more income for you.
You can begin without a large lump sum. Start small, stay consistent, and keep a long-term view. The financial freedom you want depends on that decision to begin.
This article is general information, not financial, investment, tax or legal advice. Your situation is your own, so check with a qualified professional before you act on it. See our disclaimer.