For a growing business, capital pays for expansion. The move from a stable, profitable operation to a market leader often runs into a funding gap. You have outgrown traditional bank loans, which are tied to hard assets and rigid covenants, but you do not want the heavy equity dilution that comes with a venture capital or private equity growth round. You need funding without selling a large piece of the business.
Mezzanine financing is a financial tool, often misunderstood, that fits this gap. It is a hybrid instrument that sits between senior debt and pure equity, with the flexibility and patience that ambitious growth plans need. For companies with strong cash flow and a clear plan, it can pay for acquisitions and market expansion that would otherwise stay out of reach.
Mezzanine capital behaves more like a partnership than a simple loan, so you need to understand its structure, costs, and ideal use cases before you commit. This guide takes an operator-level view and covers the tactical realities of mezzanine financing. It explains its role in your capital stack, offers a framework for deciding whether it fits, and outlines the common pitfalls to avoid. For leaders building sustainable enterprise value, knowing this layer of the capital structure is part of effective strategic financial planning for business growth.
Table of Contents
Open Table of Contents
- What is Mezzanine Financing? Beyond the Textbook Definition
- The Capital Stack Decoded: Where Mezzanine Debt Fits
- The Mezzanine Deal: How It Works in Practice
- The Growth Catalyst: Strategic Advantages of Mezzanine Capital
- Balancing Risk: The Disadvantages and Trade-Offs
- The Capital Stack Optimization Framework
- Who is Mezzanine Financing For? The Ideal Candidate Profile
- Mezzanine Financing in Action: Common Use Cases
- The Mezzanine Readiness Checklist: Are You Prepared to Raise?
- Common Pitfalls and How to Avoid Them
- The Future of Growth Capital: Alternatives to Consider
- Conclusion: Mezzanine Financing as a Strategic Lever, Not Just a Loan
What is Mezzanine Financing? Beyond the Textbook Definition
Mezzanine financing is a hybrid of debt and equity. It is structured as debt, but it is subordinated to the senior debt held by banks and other traditional lenders. In a liquidation, senior lenders get paid back first. Mezzanine lenders take on more risk than senior lenders, so they are compensated with higher returns.
Those returns come from three components:
- Cash interest: A periodic interest payment, similar to a standard loan, but at a higher rate (typically in the low-to-mid teens).
- Payment-in-kind (PIK) interest: Interest that accrues to the loan principal instead of being paid in cash. It lets the borrowing company preserve cash flow for growth initiatives, though it increases the total debt owed over time.
- Equity kicker (warrants): This is the “equity” part of the hybrid. The lender receives warrants, which are options to purchase a small amount of equity in the company at a predetermined price. If the company grows and its value increases, the warrants become valuable and give the lender a significant upside.
Think of the capital structure as a building. Senior debt is the concrete foundation: safe, secure, and unyielding. Equity is the penthouse, with the highest potential views (returns) and the most exposure. Mezzanine financing is the layer in between, adding space and function while connecting the foundation to the penthouse.
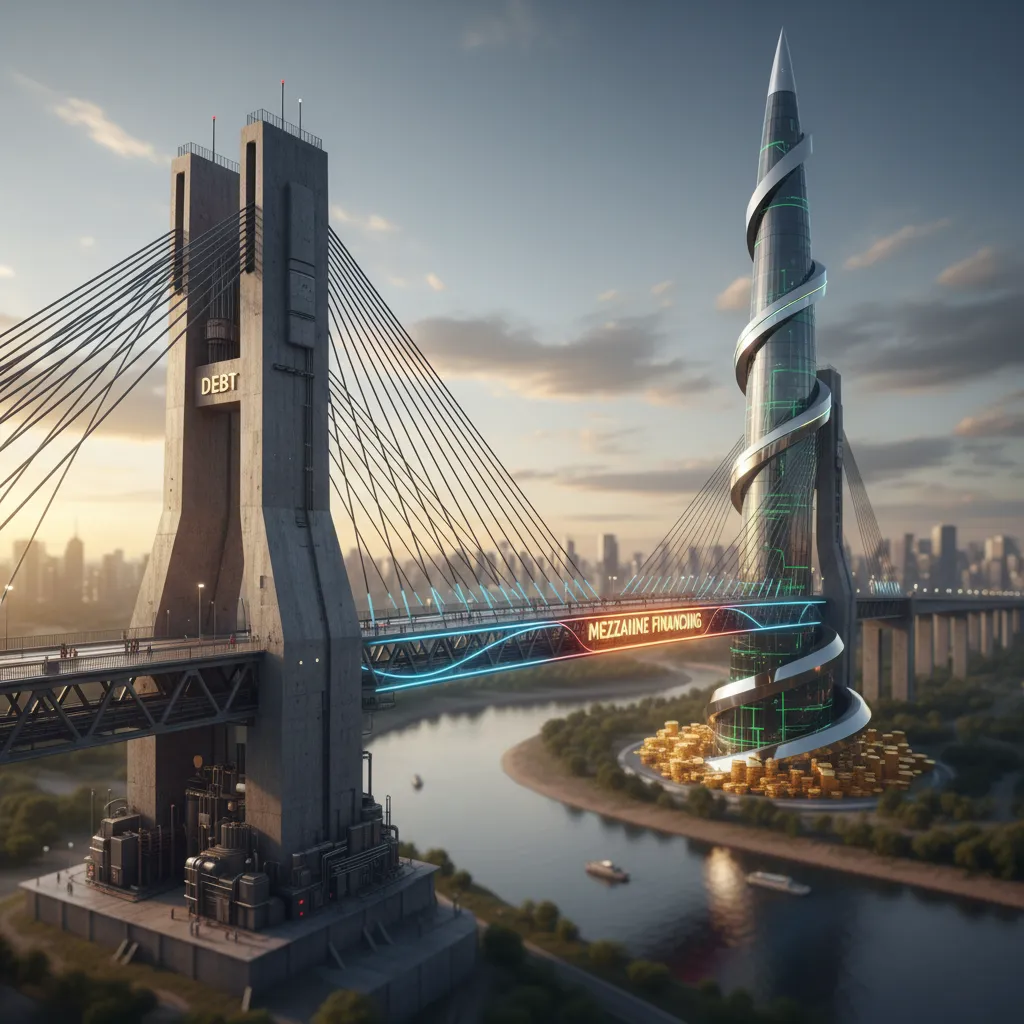
This structure makes mezzanine very different from bank debt. A bank looks almost entirely at a company’s assets and historical cash flow to limit downside risk. A mezzanine lender looks at the company’s future growth potential. They underwrite the loan based on the business’s ability to execute its growth plan, because their real return comes through the equity kicker.
The Capital Stack Decoded: Where Mezzanine Debt Fits
To understand mezzanine financing, you need to know its position in the corporate capital stack. The capital stack is the hierarchy of all the capital sources a company uses to finance its operations, ranked by priority of repayment in a liquidation.
Here is a simplified breakdown from lowest risk to highest risk:
- Senior debt: This is the safest position. It is typically secured by the company’s assets (receivables, inventory, property), and lenders include commercial banks. They have first claim on assets in a bankruptcy and are paid first, which makes this the cheapest form of capital.
- Mezzanine debt: Positioned directly below senior debt, it is unsecured and subordinate. Mezzanine lenders only get paid after all senior debt obligations are met. That higher risk justifies the higher interest rates and the equity kicker.
- Preferred equity: A class of equity that has priority over common equity in receiving dividends and liquidation proceeds. It often doesn’t carry voting rights.
- Common equity: The highest-risk, highest-return layer, held by founders, employees, and equity investors. Equity holders have the last claim on assets but also keep all the upside after debt holders are paid.
This hierarchy, often called the “payment waterfall,” is a big part of why business owners like mezzanine financing. It lets them bring in significant capital without disrupting the existing senior debt relationship or giving up the control and upside that come with a major equity round.
The Mezzanine Deal: How It Works in Practice
Securing mezzanine financing is more involved than applying for a bank loan. It takes a compelling growth story and strong financial discipline.
The typical process unfolds in these stages:
- Identifying the need: Mezzanine capital is event-driven. The need is usually tied to a specific strategic initiative, such as funding a major acquisition, financing a management buyout, or paying for a rapid expansion into a new market.
- Finding the right partner: Mezzanine lenders are not banks. They are specialized funds, business development companies (BDCs), or the private credit arms of private equity firms. Look for a partner with deep expertise in your industry who offers more than capital, such as strategic guidance and useful network connections.
- Due diligence and structuring: This is an intensive phase. The lender will do deep due diligence on your company’s financials, management team, market position, and growth projections. The deal structure is then negotiated around the main terms.
- Negotiating key terms:
- Interest rate & PIK: What is the blend of cash-pay vs. deferred interest?
- Equity warrants: How much of the company is the lender entitled to via warrants? (Typically 1-5%).
- Covenants: These are rules the company must follow. Mezzanine covenants are usually less restrictive than senior debt covenants and focus on performance metrics like maintaining a certain EBITDA level rather than strict balance sheet ratios.
- Prepayment penalties: Can you repay the loan early, and if so, what are the fees?
- Post-closing partnership: Unlike a bank, a mezzanine lender is an active partner. They may request a board observer seat and will expect regular financial reporting and strategy updates. Their success is tied directly to yours.
The Growth Catalyst: Strategic Advantages of Mezzanine Capital
For the right company at the right time, mezzanine financing offers benefits that other capital sources can’t match.
- Minimized equity dilution: This is the main draw. A traditional growth equity round might require selling 20-40% of the company, while the warrants in a mezzanine deal typically result in only single-digit percentage dilution. Existing owners keep control and capture more of the future upside.
- Patience and flexibility: Loan terms are often five to seven years, with no principal payments (amortization) required until maturity. The company can reinvest its cash flow into the growth initiatives the capital was raised to fund.
- Tax advantages: As a form of debt, the interest payments (both cash and PIK) are generally tax-deductible, which lowers the effective cost of capital for the business.
- Access to strategic partners: Reputable mezzanine funds bring more than money. Their teams often include experienced operators and investors who can advise on everything from future acquisitions to operational improvements.
- Less restrictive than senior debt: The covenants are performance-based, not asset-based. A growing company gets more operational freedom than it would under a bank loan that might restrict capital expenditures or other growth-related spending.
Balancing Risk: The Disadvantages and Trade-Offs
Mezzanine financing also carries significant risks and costs that must be managed carefully.
- Higher cost of capital: Combine the cash interest, PIK interest, and the value of the equity warrants, and the all-in cost of mezzanine capital is typically in the 15-20% range. That is significantly more expensive than senior debt.
- Potential for dilution: It dilutes less than a full equity round, but the warrants still represent a future claim on your company’s value. If the company does very well, that small percentage can become worth a lot.
- Added debt burden: It is still debt. The company must generate enough cash flow to service the interest payments and eventually repay the principal. Missing growth projections can strain the balance sheet.
- Risk of ceding influence: If financial covenants are breached, mezzanine lenders often have the right to step in and take a more active role in the company, sometimes even taking control of the board. This is why mezzanine belongs in any strategic business debt management plan.
- Complex legal agreements: The loan documents are heavily negotiated and complex. Companies need experienced legal and financial advisors to work through the terms and protect their interests.
The Capital Stack Optimization Framework
Deciding whether mezzanine financing is the right choice takes a disciplined assessment. Needing money is only part of it, and the capital source also has to match your stage, goals, and risk tolerance. We call this the Capital Stack Optimization Framework.
The framework evaluates your business across three pillars:
| Pillar | Key Questions | Implication for Mezzanine Financing |
|---|---|---|
| 1. Growth Velocity & Use of Funds | Is the goal a specific, definable project (like an acquisition) or open-ended R&D? Are you aiming for 30% annual growth or 300%? | Mezzanine is ideal for funding discrete, high-ROI projects in moderately growing companies. Hyper-growth, cash-burning businesses are better suited for venture capital for startups. |
| 2. Asset & Cash Flow Profile | Does your business generate consistent, predictable free cash flow? What is your EBITDA? Do you have a strong asset base? | A strong history of positive and stable EBITDA (typically $3M+) is a non-negotiable prerequisite for servicing mezzanine debt. Businesses without predictable cash flow cannot support it. |
| 3. Control & Dilution Tolerance | How important is it for the current ownership to retain majority control and governance? Are you willing to trade a board seat for capital? | Founders with a low tolerance for equity dilution are prime candidates. Mezzanine financing allows them to raise growth capital while preserving their ownership stake far more than a PE or VC round would. |
With this framework, a leadership team can replace a generic “we need capital” discussion with an analysis of which financing instrument best fits their long-term vision.
Who is Mezzanine Financing For? The Ideal Candidate Profile
Mezzanine financing does not suit every business. It is designed for a certain type of company at a particular stage of its lifecycle.
The ideal candidate typically has these characteristics:
- Established and profitable: A consistent history of revenue and, above all, positive EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization). Lenders generally look for at least $3 million to $5 million in annual EBITDA.
- Stable cash flows: The business must show it can generate enough cash to cover the interest payments on both its senior and mezzanine debt.
- Proven business model: This is not for early-stage companies still looking for product-market fit. The business model should be mature, with a defensible market position and a loyal customer base.
- A strong management team: Lenders are betting on the team as much as on the business. They want a seasoned leadership team with a clear record of execution.
- A clear use of funds: The capital must be earmarked for a specific, value-accretive purpose, like an acquisition or a major expansion project with a well-defined and believable ROI.
Startups, companies with volatile cash flows, and businesses in turnaround situations are generally not suitable candidates for mezzanine financing.
Mezzanine Financing in Action: Common Use Cases
Mezzanine capital most often shows up in these scenarios:
- Growth & expansion capital: Funding new locations, expansion into new geographic markets, or the launch of a new product line. Because the capital is patient, these initiatives can mature before significant cash is needed for principal repayment.
- Acquisition financing: It is a core component of financing strategies for acquisitions. A company might use senior debt for a portion of the purchase price, its own cash for another, and mezzanine financing to bridge the remaining gap in the funding for a strategic M&A deal.
- Management buyouts (MBOs) & leveraged buyouts (LBOs): Mezzanine financing is common in transactions where a management team or a private equity firm buys out the existing owners of a company. It provides the leverage to complete the purchase without contributing the entire amount in equity.
- Recapitalizations & shareholder buyouts: It can be used to restructure a company’s balance sheet, such as buying out a passive or retiring shareholder. The remaining active owners can then consolidate control without draining the company’s operational cash.
The Mezzanine Readiness Checklist: Are You Prepared to Raise?
Approaching mezzanine lenders without preparation tends to end badly. Before you start serious conversations, make sure you have a comprehensive data room with the following:
- [ ] Audited Financials: At least three years of historical, audited financial statements.
- [ ] Detailed Financial Projections: A financial model showing a base case, upside case, and downside case for the next 3-5 years. It must show how the new capital will be deployed and the expected return.
- [ ] Quality of Earnings (QoE) Report: Many sophisticated lenders will require a third-party QoE report to validate the company’s EBITDA.
- [ ] Comprehensive Business Plan: A detailed document covering the company’s history, market position, competitive advantages, management team, and growth strategy.
- [ ] Clear Use of Funds Memorandum: A specific document detailing how every dollar of the financing will be used and the timeline for deployment.
- [ ] Clean Cap Table & Corporate Structure: Well-organized documentation of the company’s ownership and legal structure.
- [ ] Experienced Advisory Team: Have you engaged an investment banker, M&A advisor, or experienced corporate lawyer? Their expertise helps in working through the process and securing favorable terms.
Common Pitfalls and How to Avoid Them
Mezzanine financing carries risks that can cripple a company if they are not managed properly.
- Over-leverage: Taking on too much debt relative to your cash flow. Avoidance: Be realistic in your financial projections. Stress-test your model against a downturn to make sure you can still service your debt in a worst-case scenario.
- Misaligned partners: Choosing a lender who doesn’t understand your industry or who has a different time horizon for their investment. Avoidance: Do reverse due diligence. Speak to the lender’s other portfolio companies to understand their style. Are they patient partners or aggressive financiers?
- Ignoring the fine print: Covenants, prepayment penalties, and default triggers can have severe consequences. Avoidance: Hire experienced legal counsel who specializes in these transactions. Model out every scenario to understand the implications of each term.
- Missed growth projections: Failing to hit the aggressive growth targets you promised is the fastest way to breach a covenant. Avoidance: Under-promise and over-deliver. Your projections should be ambitious but grounded in reality, because the lender’s trust matters most.
The Future of Growth Capital: Alternatives to Consider
Mezzanine financing is one option in a growing ecosystem of alternative growth capital. Depending on your business model and stage, you might also look at:
- Venture debt: Shorter-term loans for venture-backed startups to extend their runway between equity rounds.
- Revenue-based financing: Capital provided in exchange for a percentage of future revenues. This is a strong option for SaaS and other recurring revenue businesses. You can learn more about revenue-based financing for strategic growth.
- Private credit funds: A broad category of non-bank lenders that provide various forms of debt, including direct lending that can sometimes compete with mezzanine offerings.
Conclusion: Mezzanine Financing as a Strategic Lever, Not Just a Loan
Mezzanine financing is a sophisticated instrument for established, cash-flow-positive companies at a growth inflection point. It sits between cheaper, less flexible senior debt and more expensive, highly dilutive equity, and it can fund events like acquisitions, expansions, and shareholder buyouts.
It also brings complexity and cost. The decision to pursue mezzanine capital should go through a disciplined framework that weighs the need for growth against the company’s ability to service debt and the owners’ tolerance for dilution. When it is structured correctly with the right partner, founders and management teams can keep control, maximize their ownership, and build long-term enterprise value.
Built for readers, sustained by readers. Crypto donations help fund deeper research and independent analysis.
BTC: bc1q94zxw25s07hrshg6w20axqs5k5u3z4ddj7g2q9
ETH: 0x3235316354425310111551A9DaF1470505436665
This article is general information, not financial, investment, tax or legal advice. Your situation is your own, so check with a qualified professional before you act on it. See our disclaimer.