High-interest debt feels like running on a treadmill with the speed cranked up. You pour your hard-earned money into payments month after month and the balance barely moves. The cycle drains your bank account, and it also drains your mental energy and your future opportunities.
This kind of debt, most often from credit cards and personal loans, destroys wealth. Compounding interest works against you and turns a small balance into a heavy financial burden. Breaking free takes more than minimum payments. You need a clear, aggressive plan.
This guide is that plan. The usual advice to “spend less than you earn” only goes so far, so we cover the most effective payoff methods, the financial tools that can speed up your progress, and the common mistakes that keep people in debt for years.
The Hard Truth: Getting out of high-interest debt takes both math and psychology. The mathematically best path is not always the one you’ll stick with. The best strategy is the one that fits your personality, keeps you motivated, and delivers consistent results.
Table of Contents
Open Table of Contents
- What Is Considered High-Interest Debt?
- Step 1: The Unskippable Financial Audit
- The Core Payoff Strategies: Debt Snowball vs. Debt Avalanche
- The Debt-Velocity Framework: Choosing Your Optimal Strategy
- Strategic Accelerants: Tools to Supercharge Your Payoff
- Common Mistakes That Sabotage Debt Freedom
- Conclusion: From Debt Management to Wealth Creation
What Is Considered High-Interest Debt?
High-interest debt is any loan with an annual percentage rate (APR) well above the rate of inflation and secure lending benchmarks. There is no universal cutoff, but a common rule of thumb is any debt with an APR of 10% or higher. That almost always includes credit card debt, payday loans, and some personal loans.
Negative compounding is why this debt does so much damage. Say you have a $5,000 credit card balance at a 22% APR and make only minimum payments. If the minimum is a common formula of 1% of the balance plus that month’s interest, with a $25 floor, it would take about 19 years to pay it off and cost you about $8,100 in interest alone, so you would repay more than double what you originally borrowed.
Once you see the math, debt payoff looks less like a chore and more like a high-return investment. Every dollar you put toward a 22% APR debt is effectively a guaranteed, tax-free 22% return on your money.
Step 1: The Unskippable Financial Audit
Before you can choose a strategy, you need a clear picture of what you owe, and that means gathering all your debt information in one place.
Create a simple spreadsheet or use a notebook with these columns:
- Creditor: The name of the lender (e.g., Chase, Citi, SoFi).
- Total Balance: The exact amount you owe.
- Interest Rate (APR): The most important number.
- Minimum Monthly Payment: The smallest amount you are required to pay.
The exercise is often sobering, but it is the foundation of your plan. It turns a vague, anxiety-inducing cloud into a concrete list of items you can work through one at a time, and that clarity is where taking back control starts.
Once you have the list, you can see the full scope of the challenge. It gives you a tangible “hit list” for your debt. The next step is choosing the order in which you’ll attack it.
The Core Payoff Strategies: Debt Snowball vs. Debt Avalanche
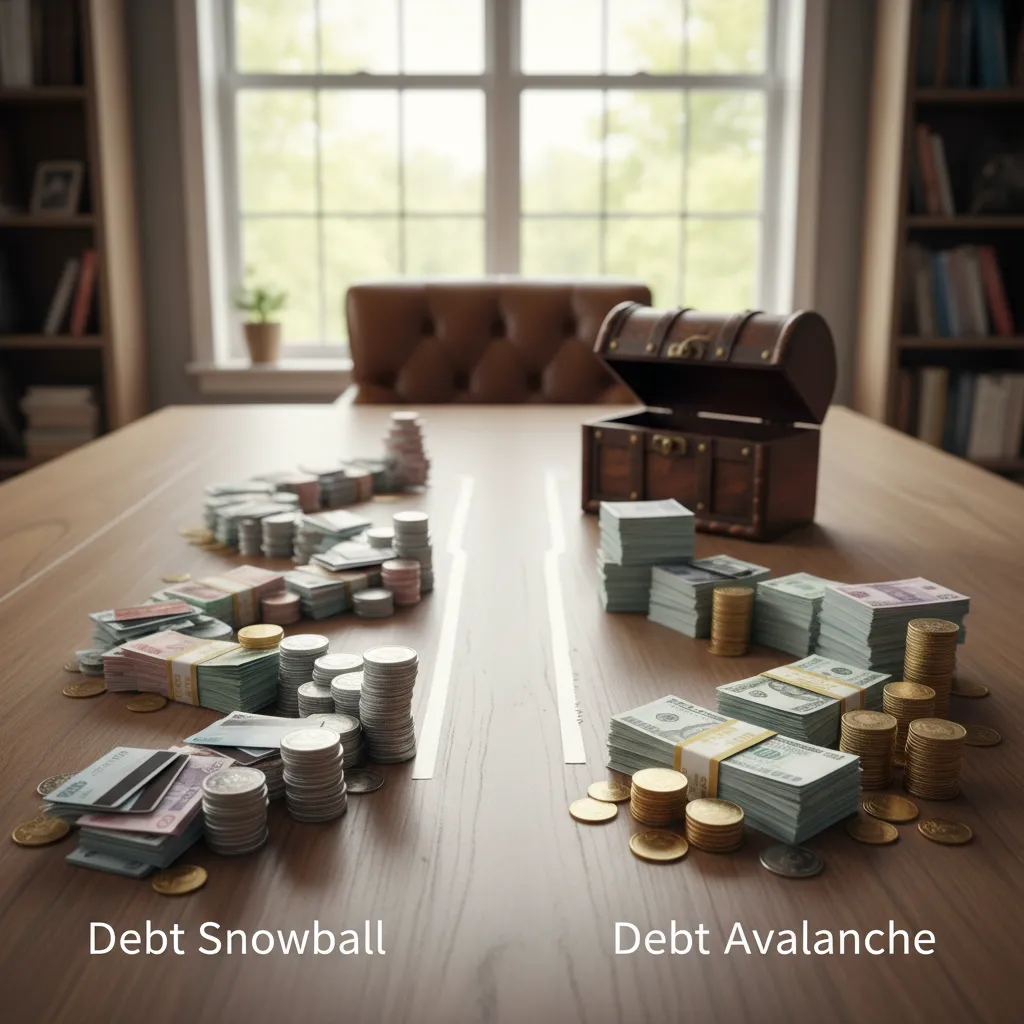
Most debates about the best way to pay off debt fast come down to two famous methods, the Debt Snowball and the Debt Avalanche. Both have you pay the minimum on all debts and then put every extra dollar toward one target debt. They differ only in how you pick that target.
The Debt Snowball Method (Psychological Wins)
The Debt Snowball method builds momentum. You target the debt with the smallest balance first, regardless of its interest rate. When that debt is paid off, you roll its payment into the payment for the next-smallest debt, which creates a “snowball” of growing payments.
- Best For: People who need quick wins to stay motivated. Seeing a debt disappear early on can give you the push to keep going.
- The Process:
- List your debts from the smallest balance to the largest.
- Pay minimums on everything except the smallest debt.
- Attack the smallest debt with all extra funds.
- Once it’s gone, apply its old payment (plus the extra funds) to the next-smallest debt.
The Debt Avalanche Method (Mathematical Optimization)
The Debt Avalanche method is the most efficient on cost. You target the debt with the highest interest rate (APR) first, regardless of its balance. This approach saves you the most money in interest over the long run.
- Best For: People who are disciplined, motivated by numbers, and want to minimize the total cost of their debt.
- The Process:
- List your debts from the highest APR to the lowest.
- Pay minimums on everything except the highest-APR debt.
- Attack the highest-APR debt with all extra funds.
- Once it’s gone, apply its old payment (plus the extra funds) to the next-highest-APR debt.
| Aspect | Debt Snowball | Debt Avalanche |
|---|---|---|
| Attack Order | Smallest balance first | Highest interest rate first |
| Primary Advantage | Psychological momentum | Saves the most money |
| Key Benefit | Quick, motivating wins | Mathematical efficiency |
| Potential Downside | May cost more in interest | May take longer to get the first win |
The Hard Truth: The Avalanche method is mathematically better, but studies have found the Snowball method has a higher completion rate. The feeling of progress is a strong motivator, and the psychological side of personal finance counts.
The Debt-Velocity Framework: Choosing Your Optimal Strategy
Choosing between Snowball and Avalanche can lead to analysis paralysis. To simplify it, we’ve created The Debt-Velocity Framework, which helps you pick a path based on your financial situation and what keeps you motivated.
The framework rests on two questions:
- What is the gap between your smallest debt and your highest-APR debt? (Is your smallest debt also your highest-APR debt, or are they very different?)
- What motivates you more: saving money or seeing rapid progress?
Here’s how to use the framework:
-
Scenario 1: The Perfect Alignment
- If… your smallest debt is also your highest-interest debt (or close to it).
- Then… The choice is easy. You get the psychological win of the Snowball and the mathematical efficiency of the Avalanche. Start there immediately.
-
Scenario 2: The Motivation Play
- If… you feel overwhelmed and need a quick win to build confidence, and your smallest debt is relatively easy to eliminate.
- Then… Use the Debt Snowball. The momentum from knocking out that first debt is worth more than the extra interest you might pay.
-
Scenario 3: The Optimization Play
- If… you are highly disciplined, your debts have very different interest rates (e.g., a 25% APR card and a 12% APR loan), and you are driven by efficiency.
- Then… Use the Debt Avalanche. The long-term savings will be substantial, and they can keep you motivated.
-
Scenario 4: The Hybrid Approach
- If… you have one very small “nuisance” debt and then several large, high-interest debts.
- Then… Use a Hybrid Strategy. Pay off the tiny debt first for the quick win (a mini-Snowball), then switch to the Avalanche method to tackle the high-APR debts.
Strategic Accelerants: Tools to Supercharge Your Payoff
Once you’ve chosen your core strategy, specific financial products can lower your interest rates and speed up your progress. They work well, but only if you use them with discipline.
Debt Consolidation Loans
A debt consolidation loan is a personal loan used to pay off several other debts. You end up with a single monthly payment, often at a much lower interest rate than your credit cards. This can be a strong move for strategic debt consolidation.
- How it works: You take out one loan to pay off all your high-interest balances.
- Pros: Simplifies payments and gives you a fixed interest rate and a clear payoff date.
- Cons: Requires a good credit score to qualify for a low rate, and an origination fee may apply.
Balance Transfer Credit Cards
These cards offer a 0% introductory APR period (typically 12-21 months) on balances you transfer from other cards. Your payments then go entirely toward the principal and none toward interest.
- How it works: You open a new card and transfer your existing high-interest balances to it.
- Pros: Pauses interest, so you can reduce the principal quickly.
- Cons (The Hard Truth):
- Most cards charge a balance transfer fee (3-5% of the amount transferred).
- If you don’t pay off the balance by the end of the intro period, the remaining balance is subject to a high standard APR.
- The biggest danger is treating the newly freed-up credit on your old cards as an invitation to spend more.
These tools only work if you stop adding new debt. They help you reach the goal and do not solve the problem on their own. Improving your financial habits and managing your cash flow matters as much as the tools you use.
Common Mistakes That Sabotage Debt Freedom
The road to becoming debt-free has a few common pitfalls. Knowing them is the best way to stay on track.
- Not Building an Emergency Fund: Many people throw every spare dollar at debt. When an unexpected expense arrives (car repair, medical bill), they have no choice but to borrow again. Save at least $1,000 in a separate account as a buffer before you get aggressive with debt payoff.
- Closing Credit Cards Immediately After Payoff: It feels satisfying, but closing old credit card accounts can lower your average age of accounts and raise your credit utilization ratio, which can temporarily damage your credit score. It’s often better to keep the account open with a zero balance.
- Lifestyle Inflation: As you pay off debts, your monthly cash flow grows, and it’s tempting to reward yourself by spending more. Redirect that freed-up money to your next debt target or into savings and investments if you want to build wealth.
- Ignoring the Root Cause: Debt is often a symptom of other issues, such as spending habits, lack of a budget, or emotional triggers. If you don’t address the behaviors that led to the debt, you are likely to end up back where you started.
Conclusion: From Debt Management to Wealth Creation
Paying off high-interest debt is one of the most powerful financial moves you can make. It is a direct investment in your future that frees up capital and mental energy for your life goals. The journey takes focus, discipline, and a clear strategy.
Do a thorough audit, choose a payoff method that fits your psychology using the Debt-Velocity Framework, and use tools like consolidation loans where they make sense, and you can shorten your timeline considerably. The goal is a zero balance and also the habits that make up the foundation of long-term financial planning.
Built for readers, sustained by readers. Crypto donations help fund deeper research and independent analysis.
This article is general information, not financial, investment, tax or legal advice. Your situation is your own, so check with a qualified professional before you act on it. See our disclaimer.