Building significant wealth is a real achievement. Preserving it, growing it, and passing it across generations is a different job, and standard financial advice rarely covers it. For high-net-worth individuals (HNWIs), the financial picture is more than a larger version of the average investor’s. It is more complex, with its own opportunities, risks, and responsibilities.
Financial planning for high-net-worth individuals goes well past basic portfolio allocation and retirement savings. It combines investment management, proactive tax mitigation, estate planning, and asset protection into one strategy. It takes the same discipline as strategic financial planning for business growth, applied to your personal and family enterprise. The goal moves from accumulating wealth to preserving it and leaving a deliberate legacy.
This guide goes past surface-level advice to lay out a blueprint for HNWIs and their families. It covers the core pillars of wealth management, introduces a framework for tying your strategy together, and gives you checklists for building the advisory team you need.
Table of Contents
Open Table of Contents
- Beyond Accumulation: The Unique Financial Landscape of HNWIs
- The Four Pillars of High-Net-Worth Financial Strategy
- Introducing the Integrated Wealth Blueprint: A Proprietary Framework
- Pillar 1: Advanced Investment Management for HNWIs
- Pillar 2: Strategic Tax Planning to Preserve Wealth
- Pillar 3: Estate & Legacy Planning for Future Generations
- Pillar 4: Asset Protection and Sophisticated Risk Management
- Building Your A-Team: How to Choose the Best Financial Advisors
- Common Mistakes in High-Net-Worth Financial Planning (And How to Avoid Them)
- From Wealth to Legacy: A Strategic Conclusion
Beyond Accumulation: The Unique Financial Landscape of HNWIs
The term “high-net-worth individual” typically refers to someone with at least $1 million in liquid financial assets. This is often split into tiers:
- High-Net-Worth Individuals (HNWIs): $1 million to $5 million
- Very-High-Net-Worth Individuals (VHNWIs): $5 million to $30 million
- Ultra-High-Net-Worth Individuals (UHNWIs): $30 million or more
Whatever the tier, crossing the HNWI threshold brings financial challenges and opportunities that conventional wisdom does not handle well. Standard advice is designed for mass-market accumulation and misses several variables that matter at this level:
- Tax complexity: HNWIs face higher marginal income tax rates, capital gains, alternative minimum tax (AMT), and potential estate and gift taxes. Almost every investment decision has tax consequences.
- Access to private investments: Wealth opens doors that are closed to the general public, such as private equity, venture capital, hedge funds, and direct real estate investments. These call for specialized due diligence and an understanding of illiquid markets.
- Concentrated positions: Founders, executives, and early employees often hold a large stake in a single company, which creates risk and a need for diversification and hedging.
- Asset protection: Substantial wealth can attract frivolous lawsuits and other threats, so protecting assets from creditors and legal challenges becomes a priority.
- Multi-generational dynamics: Planning covers a whole family, often across several generations, rather than one person or a couple. That means preparing heirs, building financial literacy, and handling family dynamics.
- Legacy and philanthropy: HNWIs can have a lasting impact through philanthropy, which takes careful planning to get both the social return and the tax efficiency.
Handling all of this means shifting from an employee saving for retirement to the CEO of a complex family enterprise.
The Four Pillars of High-Net-Worth Financial Strategy
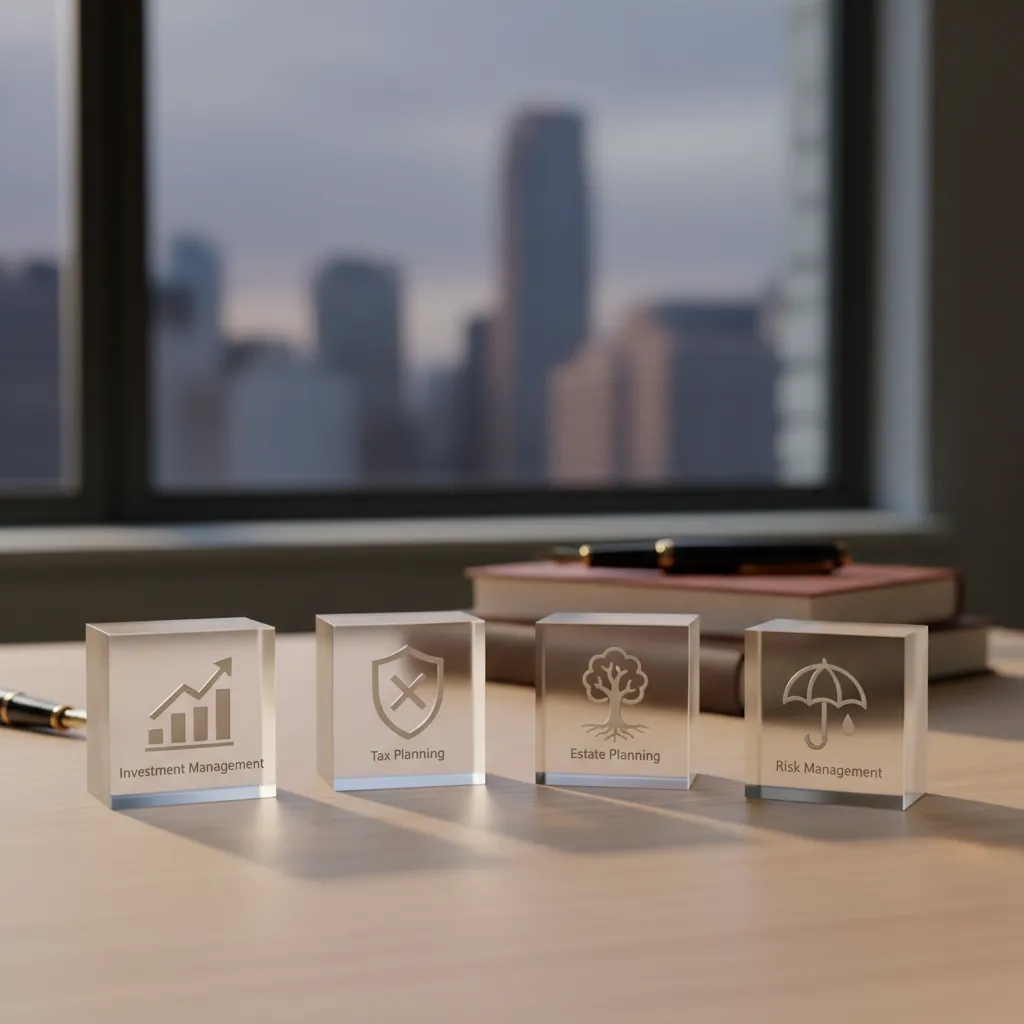
Effective HNWI financial planning is one integrated system built on four interdependent pillars, rather than a collection of separate services. A decision in one area affects the others, so wealth management has to coordinate the pillars into a single strategy.
- Advanced investment management: This goes well beyond a mix of stocks and bonds. It includes accessing private markets, using hedging techniques, managing concentrated positions, and optimizing the whole portfolio for tax efficiency.
- Strategic tax planning: The focus moves from reactive tax preparation to year-round planning. The goal is to legally minimize taxes on income, capital gains, and estate transfers, which leaves more wealth for growth and legacy.
- Estate and legacy planning: This pillar gets your wealth to the people and causes you care about as efficiently as possible. It means designing a plan that reflects your values and prepares the next generation for their inheritance.
- Risk management and asset protection: This means identifying threats, from market volatility and inflation to lawsuits and cybersecurity breaches, and putting strategies in place to insulate your wealth from them.
When your investment advisor, CPA, and attorney don’t talk to each other, you get inefficiency and missed opportunities. The strongest strategies come from advisors who work together.
Introducing the Integrated Wealth Blueprint: A Proprietary Framework
Managing four pillars well takes a structured, repeatable process. We call ours the Integrated Wealth Blueprint, a four-phase framework for building a flexible, resilient, and personalized financial strategy.
| Phase | Focus | Key Activities |
|---|---|---|
| Phase 1: Discovery & Goal Alignment | Understanding the “Why” | Deep-dive interviews to clarify financial goals, risk tolerance, family values, philanthropic intent, and liquidity needs. Mapping the entire family balance sheet. |
| Phase 2: Strategic Architecture Design | Building the “How” | Crafting a customized Investment Policy Statement (IPS). Designing tax, estate, and asset protection structures. Stress-testing scenarios and modeling long-term outcomes. |
| Phase 3: Implementation & Execution | Making it “Happen” | Deploying capital into target allocations. Establishing trusts and legal entities. Coordinating with CPAs and attorneys to execute the plan. Onboarding assets and technology. |
| Phase 4: Dynamic Monitoring & Adaptation | Ensuring it “Lasts” | Continuous performance monitoring, regular portfolio rebalancing, proactive tax-loss harvesting, and annual strategic reviews to adapt the plan to life events, market shifts, and regulatory changes. |
The framework turns financial planning from a static document into a strategy that changes as you and your family do.
Pillar 1: Advanced Investment Management for HNWIs
For HNWIs, the investment universe is wide. The task is to build an institutional-quality portfolio that balances growth, income, and risk while staying tax-aware.
Diversification Beyond Public Markets
Public stocks and bonds usually remain a core holding, but real diversification for HNWIs includes a meaningful allocation to alternative investments for strategic diversification. These assets have a low correlation to public markets, and they can offer higher returns and lower overall portfolio volatility.
- Private equity: Investing directly in private companies, either through funds or co-investments. This gives access to high-growth businesses before they go public. See our guide on private equity for individual investors.
- Venture capital: A subset of private equity focused on early-stage startups with high growth potential. Learn more about venture capital for startups.
- Private credit: Lending money directly to businesses, often at attractive yields with creditor protections.
- Real estate: Direct ownership of commercial properties, or investing in private real estate funds that hold a portfolio of assets. Explore our guide to commercial real estate investing.
Tax-Advantaged Investing Strategies
Look at every investment decision through a tax lens. The goal is to maximize after-tax returns.
- Tax-loss harvesting: Selling investments at a loss to offset capital gains taxes on other investments, done on a regular schedule. Over time this can add significant value. Our guide to tax-loss harvesting goes into more detail.
- Asset location: Placing each type of asset in the most tax-efficient account. For example, high-growth assets go in tax-exempt Roth accounts and income-generating assets in tax-deferred accounts.
- Municipal bonds: Interest from these bonds is often exempt from federal (and sometimes state and local) income tax, which makes them attractive for investors in high tax brackets.
Concentrated Stock Positions & Hedging
For founders and executives, a single stock position can be most of their net worth, and that is a large risk. Ways to manage it include:
- Rule 10b5-1 plans: A pre-arranged, automated plan for insiders to sell company stock over time, which gives a defense against accusations of insider trading.
- Hedging strategies: Using financial instruments like options collars to protect against a significant drop in the stock’s price while keeping some upside.
- Exchange funds: A vehicle that lets investors with concentrated positions swap their shares for an interest in a diversified portfolio of other concentrated stocks, deferring the capital gains tax.
Pillar 2: Strategic Tax Planning to Preserve Wealth
With high income and substantial assets, a large share of your wealth can go to taxes unless you plan carefully. Strategic tax planning builds tax efficiency into every financial decision.
Income Tax Mitigation
- Maximizing tax-deferred growth: Fully funding available retirement accounts like 401(k)s and IRAs, and considering cash balance plans for business owners.
- Charitable planning: Using vehicles like Donor-Advised Funds (DAFs) to bunch several years of charitable contributions into one year for a larger tax deduction.
- State residency planning: For those with flexibility, establishing residency in a state with no or low income tax can mean substantial savings.
Capital Gains Optimization
- Long-term holding periods: Holding appreciated assets for more than one year to qualify for lower long-term capital gains tax rates.
- Qualified Small Business Stock (QSBS): Section 1202 of the tax code allows a significant exclusion of capital gains tax on the sale of stock from qualified small businesses, a major benefit for early investors and founders.
- Opportunity Zones: A program that gives tax incentives for investing in designated economically distressed communities, including deferral and reduction of capital gains taxes.
Pillar 3: Estate & Legacy Planning for Future Generations
An estate plan is more than a set of legal documents. It is the instruction manual for your legacy. For HNWIs, it ensures a smooth transfer of wealth and of family values. A well-designed plan minimizes estate taxes and protects assets for future generations.
Our strategic estate planning blueprint offers a comprehensive overview.
Advanced Trust Strategies
Trusts are the cornerstone of sophisticated estate planning, and they provide control, protection, and tax efficiency.
- Revocable Living Trust: A foundational tool that holds assets during your lifetime and lets them pass to heirs outside of the lengthy and public probate process.
- Irrevocable Life Insurance Trust (ILIT): Owns a life insurance policy, which removes the proceeds from your taxable estate and gives your heirs immediate, tax-free liquidity to cover estate taxes or other expenses.
- Grantor Retained Annuity Trust (GRAT): An advanced strategy where an individual transfers appreciating assets into a trust and receives an annuity payment for a set term. Any appreciation above a certain rate passes to beneficiaries free of gift and estate tax.
- Dynasty Trust: A long-term trust designed to pass wealth through multiple generations while minimizing transfer taxes and protecting assets for beneficiaries.
Strategic Philanthropy
For many HNWIs, philanthropy is a core part of their legacy. Planned giving can serve charitable goals and bring tax benefits at the same time.
- Donor-Advised Funds (DAFs): These let you make a charitable contribution, receive an immediate tax deduction, and then recommend grants to your favorite charities over time.
- Private foundations: A separate legal entity that gives more control and family involvement but has higher administrative costs and complexity.
- Learn more about integrating giving into your plan with our guide on strategic philanthropy and wealth transfer.
Pillar 4: Asset Protection and Sophisticated Risk Management
Preserving wealth comes first. A comprehensive plan has to shield your assets from threats such as litigation, creditors, and divorce.
Our guide to strategic asset protection covers this in detail.
Legal Structures and Titling
- Limited Liability Companies (LLCs) and Family Limited Partnerships (FLPs): These legal entities can own assets like real estate or business interests, which creates a legal barrier between your personal assets and business liabilities.
- Proper asset titling: Owning assets in the correct legal structure (for example, in the name of a trust) is a simple but effective asset protection tool.
Advanced Insurance Strategies
Insurance is a main line of defense against catastrophic financial loss.
- High-limit umbrella insurance: Adds a layer of liability coverage above the limits of your homeowners and auto insurance policies. HNWIs should carry policies of $5 million or more.
- Private Placement Life Insurance (PPLI): A tool for UHNWIs that combines the tax benefits of life insurance with access to a wider range of investment options, including hedge funds.
- Cybersecurity insurance: As personal and financial lives move online, protecting against cyber theft and fraud matters more. A cybersecurity insurance guide can help you understand the options.
Building Your A-Team: How to Choose the Best Financial Advisors
No single person can be an expert in every part of high-net-worth financial planning. You need a coordinated team of specialists who work together.
The Key Players: Who You Need on Your Team
- Wealth Manager / Financial Advisor: The “quarterback” of the team, responsible for developing and coordinating the overall financial strategy.
- Certified Public Accountant (CPA): Specializes in tax planning and preparation.
- Estate Planning Attorney: Drafts the legal documents (wills, trusts) needed to carry out your legacy plan.
- Insurance Specialist: Analyzes risks and secures appropriate life, disability, property, and liability coverage.
The Fiduciary Standard: A Non-Negotiable Requirement
When you choose an advisor, the most important thing to confirm is that they are a fiduciary. A fiduciary is legally and ethically bound to act in your best interest at all times. That differs from the less stringent “suitability” standard that brokers often follow. Ask any potential advisor, in writing, whether they are a fiduciary. Our guide on finding a fiduciary financial advisor explains why this matters.
A Checklist for Vetting Potential Advisors
Use this checklist to do due diligence on any wealth management firm or advisor you consider:
- [ ] Credentials and expertise: Do they hold premier designations like Certified Financial Planner™ (CFP®), Chartered Financial Analyst (CFA), or CPA/PFS? Do they have demonstrable experience with clients of your net worth and complexity?
- [ ] Fee structure: Are they “fee-only,” meaning client fees are their only compensation and they earn no commissions from selling products? That aligns their interests with yours. Find out exactly how they are paid and review their wealth management fees to optimize value.
- [ ] Fiduciary oath: Will they sign a fiduciary oath in writing?
- [ ] Investment philosophy: Is their investment approach evidence-based, disciplined, and in line with your own views?
- [ ] Team and services: Do they have in-house specialists or a strong network of outside experts for tax and legal matters? Do they offer comprehensive planning beyond investments?
- [ ] Technology and reporting: Is their client portal easy to use? Is their performance reporting clear and complete?
- [ ] Client references: Will they let you speak with current clients who have a similar financial profile?
Common Mistakes in High-Net-Worth Financial Planning (And How to Avoid Them)
Even sophisticated individuals fall into common traps, and knowing them is the first step to avoiding them.
- Confusing investment management with wealth management: Investment management is one piece of the puzzle. Wealth management integrates all four pillars. Don’t let a stockbroker pass as a comprehensive wealth advisor.
- Neglecting the “soft” side: If you never talk with family about wealth and inheritance, you risk conflict and unprepared heirs. A good plan includes family meetings and education for the next generation.
- Overlooking liability and risk: Assuming your wealth is safe is a dangerous oversight. Asset protection and insurance strategies are not optional.
- Letting the “tax tail wag the dog”: Tax efficiency matters, but it should not be the only driver of decisions. Avoid making a poor investment just for a potential tax break.
- Sticking with an outdated or mismatched advisor: The advisor who helped you build your first million may not have the expertise to manage a ten or fifty-million-dollar estate. Review your advisory relationship periodically to make sure it still meets your needs.
From Wealth to Legacy: A Strategic Conclusion
Financial planning for high-net-worth individuals is an ongoing process that takes expertise, integration, and a long view. It means moving from the tactics of accumulation to a strategy for preserving, growing, and using your wealth.
Understand the four core pillars (investments, tax, estate, and risk management), adopt an integrated framework to manage them, and you can move forward with confidence. Build a team of fiduciary experts who can give you the specialized guidance to handle the complexity and reach your most important goals.
This article is general information, not financial, investment, tax or legal advice. Your situation is your own, so check with a qualified professional before you act on it. See our disclaimer.